Credit & Bond Ratings in Cambodia: Building Trust, Market Discipline And Investor Access

Cambodia’s financial system is entering a more important stage of development.

For many years, economic growth was mainly supported by bank lending, foreign direct investment, real estate activity, trade, manufacturing, tourism and private-sector expansion. That model helped Cambodia grow quickly, but the next stage requires deeper capital markets, stronger issuer transparency, better risk pricing and wider investor participation.


Credit and Bond Ratings

A credit rating is not simply a letter grade. It is an independent opinion on an issuer’s ability and willingness to meet financial obligations. A bond rating goes further by assessing the specific risk of a debt instrument, including repayment capacity, security structure, guarantees, covenants, recovery prospects and instrument-level protections.

For Cambodia, ratings matter because they help move the market from relationship-based lending toward transparent, rules-based capital formation.

Cambodia’s economy remains sizeable and investable, but it also faces a more complex environment. The World Bank estimated Cambodia’s 2025 GDP at about US$50.5 billion, with real GDP growth estimated at 4.8% in 2025, projected to moderate to 3.9% in 2026 and recover to 4.9% in 2027. The same outlook notes that manufacturing FDI remains an important support, with FDI inflows reaching US$5.1 billion in 2025, or 10.1% of GDP.

At the same time, Cambodia’s capital market is becoming more active. The National Bank of Cambodia’s Financial Stability Review 2025 noted that the government bond market expanded significantly, with total government bond issuance reaching KHR 691.2 billion, or about US$172.2 million, and government bonds outstanding reaching KHR 990.5 billion. Corporate bonds also grew strongly, with outstanding corporate bonds reaching KHR 1.5 trillion, or about US$379.1 million, up 172.5% from the previous year.

That is precisely why ratings are no longer optional market decoration. They are becoming part of Cambodia’s financial infrastructure.


Why Credit & Bond Ratings Matter for Cambodia

Independent ratings can support Cambodia in several practical ways.

1/ First, they reduce information gaps. Investors, banks, regulators and market participants need a common language to understand credit risk. Ratings provide that language by converting complex financial, legal, operational and governance analysis into an understandable risk opinion.

2/ Second, ratings can help lower funding friction. A transparent rating does not guarantee cheaper funding, but it can make funding discussions more disciplined. Issuers with stronger governance, better disclosure, predictable cash flows and stronger risk controls are generally better positioned to attract investors.

3/ Third, ratings help Cambodia broaden its investor base. Domestic investors may understand local market conditions, but foreign investors normally require more structured disclosure. They need to understand sovereign risk, legal enforceability, foreign-exchange risk, transferability, recovery assumptions, ESG credibility and cross-border repayment mechanics.

4/ Fourth, ratings support regional credibility. Cambodia is not competing only inside Cambodia. It is competing for capital against Vietnam, Thailand, Malaysia, Indonesia and other emerging ASEAN markets. A stronger rating culture helps Cambodian issuers present themselves in a format regional and international investors can understand.

5/ Fifth, ratings strengthen market discipline. Once issuers know that governance, disclosure, leverage, liquidity, covenants, related-party exposure, ESG practices and risk management will be independently assessed, the quality of corporate behaviour tends to improve.

This aligns with Cambodia’s securities-sector development priorities. The Securities Sector Development Strategy 2025–2035 notes that Cambodia’s securities regulatory framework is robust and aligned with IOSCO principles and international practices, while also recognising that the development of the government securities market is important for deepening the corporate bond market. The same strategy also identifies constraints, including limited domestic savings capacity and the high level of US dollar transactions in Cambodia.


Andersen Consulting Cambodia’s Role

Andersen Consulting Cambodia is an accredited Credit Rating Agency in Cambodia, bringing independent, methodology-driven research, ratings and credit assessments to Cambodia’s developing capital market.

The firm delivers independent credit ratings, financial-strength assessments and risk analytics aligned with regulatory expectations. Public commentary has also highlighted Andersen Consulting Cambodia’s more than 25 years of regional and international ratings, research and analytical experience, combining global best practice with local market understanding.

This is important because Cambodia needs ratings that are both globally credible and locally grounded. International standards alone are not enough if they are not adapted to Cambodia’s legal, regulatory, banking, business and investor environment. Equally, local market knowledge alone is not enough if it is not supported by disciplined methodology, documentation, transparency and rating governance.

Andersen Consulting Cambodia helps bridge that gap by delivering independent, methodology-driven research, ratings and credit assessments aligned with both international standards and Cambodia’s regulatory framework. In practical terms, this helps Cambodian issuers strengthen transparency, improve investor communication, support better funding access and broaden participation from both domestic and cross-border investors.

Andersen Cambodia was recently recognised by SERC for contributions to Cambodia’s capital-market development, including support for a stronger, more transparent and more inclusive investment environment.


Beyond Regulated Ratings: SuperBankRatings

Beyond regulated credit ratings, Andersen Consulting Cambodia also deploys SuperBankRatings, a specialised financial-services research and benchmarking framework.

SuperBankRatings is positioned as Cambodia’s premier source for independent bank research, ratings, views and financial education. Its stated mission is to equip banks with strategic insights, close the information gap between banks and customers, and improve transparency, governance and compliance standards.

This is especially relevant for Cambodia’s banking and financial-services sector. Regulated credit ratings assess creditworthiness. SuperBankRatings adds another layer of institutional insight by benchmarking banks on areas such as governance strength, risk discipline, innovation, sustainability performance, market positioning, product quality, transparency and customer-facing performance.

This broader benchmarking framework can enhance institutional positioning. It gives banks and financial institutions a clearer view of where they stand, where they are strong, and where they need to improve. In a developing market, this type of benchmarking can support better governance, stronger customer trust and more informed investor engagement.


Localised “kh” Ratings vs International Ratings

One of the most important issues for Cambodia is the difference between a localised Cambodian national-scale rating, often expressed as a “kh” rating, and an international or global-scale rating.

A localised “kh” rating ranks credit risk within Cambodia. For example, a “kh AAA” rating may indicate that an issuer or bond is among the strongest credit risks on a Cambodian national scale. However, it is not automatically equivalent to an international AAA rating.

The reason is simple: a national-scale rating measures relative strength inside the country, while an international rating measures risk against a broader global universe of issuers and instruments.

A Cambodian bond may therefore be very strong domestically, but receive a lower international view because foreign investors will apply additional risk tests. These may include Cambodia sovereign risk, foreign-exchange and convertibility risk, transferability risk, offtaker risk, construction risk, operating risk, legal enforceability, ESG credibility and recovery uncertainty.

This is not a weakness of the Cambodian rating system. It is a necessary distinction.

A local rating helps domestic investors understand relative risk within Cambodia. An international rating helps global investors compare the Cambodian issuer or bond against issuers in other countries.


The International Investor Risk Overlay

For Cambodia, the most useful bridge between local and international ratings is the International Investor Risk Overlay.

This overlay explains why a bond may look strong domestically but lower under an international investor lens. It does mean that both Cambodian credit rating agencies are to use the same methodology. Rather, it encourages clearer disclosure of how each agency considers international investor risk factors while preserving CRA independence.

The International Investor Risk Overlay covers:


Area

Required CRA Commentary

Sovereign ceiling

Whether the project or bond rating is constrained by Cambodia country risk, sovereign environment, regulatory conditions or broader macroeconomic limitations.

FX risk

Whether project revenue, operating costs, reserve accounts and debt obligations are denominated in the same currency, and whether FX mismatch is mitigated.

Transfer risk

Whether interest, principal and distributions can be remitted offshore to foreign investors without material restriction, delay or currency-conversion risk.

PPA risk

For power and infrastructure bonds, whether the offtaker has adequate credit strength, payment history, tariff certainty and contractual reliability.

Construction risk

Whether the project is exposed to EPC failure, delay, cost overrun, permitting, grid-connection, technical-completion or COD risk.

Operating risk

Whether the asset has reliable O&M, availability, performance-ratio assumptions, insurance coverage, monitoring systems and operating track record.

Legal risk

Whether security, trustee rights, step-in rights, account controls, enforcement rights and creditor ranking are clear and enforceable.

ESG / green bond risk

Whether the bond has credible EIA, ESMP, ICMA-aligned documentation, SPO, use-of-proceeds controls and ongoing reporting commitments.

Recovery analysis

What bondholders may reasonably recover in a default scenario, based on collateral, seniority, guarantees, legal enforceability and restructuring assumptions.


This overlay is critical for Cambodia because international investors do not only ask,

… “What is the rating?” … They ask, … “What does the rating mean, what does it not mean, where are the risks, how are they mitigated, and what happens if the transaction fails?”…


The Next Stages

Cambodia’s next stage of financial development will depend on more than growth alone.

It will depend on;

  • Trust,
  • Transparency,
  • Governance,
  • Disclosure, Investor confidence and
  • Disciplined Capital Allocation.


Credit and Bond Ratings help provide that discipline.

  • For issuers, ratings can improve credibility and investor communication.
  • For investors, ratings can support risk comparison and due diligence.
  • For regulators, ratings can support market discipline and transparency.
  • For the Kingdom, ratings can help connect domestic growth ambitions with regional and international capital.

Andersen Consulting Cambodia, as an accredited credit rating agency, is well positioned to contribute to this development by combining international methodology, local market understanding, independent research and Cambodia-specific regulatory alignment.


The broader opportunity is not simply to rate Cambodian issuers. It is to help Cambodia build a more transparent, investable and institutionally credible financial market.


 Andersen Consulting Cambodia Master Rating Scale

The Andersen Consulting Cambodia Master Rating Scale is a positive step toward clearer market communication. It provides an internationally comparable long-term credit and bond rating framework, with rating categories from AAA to D and supporting descriptions for credit quality, default probability, recovery implications and instrument-level notching considerations.

One strong feature of the Andersen Consulting Cambodia Master Rating Scale is that it separates several issues that are often confused in emerging markets.

1/ It recognises that issuer ratings and issue ratings may differ. A company may have one credit profile, but a specific bond may be stronger or weaker depending on security, guarantee support, contractual priority, structural subordination, loss severity and recovery prospects.

2/ It also makes clear that ratings are opinions, not guarantees, and that no rating should be described as risk-free. Even the highest rating category does not eliminate market risk, liquidity risk, legal risk, regulatory risk, event risk or operational risk.

3/ The scale also identifies BBB- as the common investment-grade floor, with BB+ and below generally treated as speculative grade or high yield.

This type of rating scale is valuable for Cambodia because it helps investors see rating migration, investor eligibility and risk escalation more clearly. It also helps issuers understand what separates investment-grade strength from speculative-grade vulnerability.

Andersen Consulting Cambodia Master Rating Scale

Detailed Master Rating Scale

Color coding is intended to make rating migration, investor eligibility and risk escalation visible at a glance. The international comparator is indicative and should not override local rating definitions, national-scale identifiers or transaction-specific methodology.

Andersen_Consulting_Cambodia_Master_Rating_Scale_June 2026

Disclaimer

This article is prepared for informational purposes only and reflects the independent analytical capabilities of Andersen Consulting Cambodia as a fully accredited credit rating agency and provider of financial services research and ratings under its SuperBankRatings product framework.

All ratings and assessments are based on information available at the time of analysis and are subject to ongoing surveillance and review.

Enquiries:

K H Wee-Oon

Chief Research & Rating Officer

Andersen Consulting Cambodia

E: wee-oon.kwanghwee@kh.Andersen.com

Telegram: @KHWeeOon

Your Value Today Defines Your Retirement Future: Cambodia’s Money Tree

CAMBODIA’S RETIREMENT FUTURE: Why “Value” Is No Longer Optional, It’s Survival !

Cambodia is entering a decisive phase, economically, socially, and financially.

For decades, the country’s growth story has been driven by youthful demographics, rising foreign investment, and industrial expansion.

But a quieter, more structural shift is now emerging: the future of retirement security for Cambodians.

The question is no longer whether people should save for retirement.

The real question; echoing global insights from research and rating leaders like MPF Ratings (HK) is far sharper:

Are Cambodians actually getting “value” from the money they set aside for their future?

Understanding “Value” in Retirement …  Beyond Just Saving

Globally, “value for money” in pension systems has evolved beyond simple accumulation.

It now reflects a combination of:

  • Net investment returns (after fees and inflation)
  • Cost efficiency and transparency
  • Risk management and capital preservation
  • Long-term sustainability of retirement income

In markets like Hong Kong, the Mandatory Provident Fund (MPF) has increasingly focused on whether contributors are genuinely benefiting from their investments, driving reforms around fees, transparency, and performance benchmarking.

Cambodia is now at a similar confluence … 

Cambodia’s Pension Foundations … Quietly Strengthening

The Cambodian government has taken meaningful steps to build a structured retirement ecosystem, particularly through:

  • National Social Security Fund (NSSF)
  • Policy direction from the National Bank of Cambodia
  • Broader financial sector reforms aligned with long-term development strategies

The NSSF pension scheme, formally rolled out in recent years, represents a major milestone. It shifts Cambodia from an informal, family-dependent retirement culture toward a systematic, contribution-based model.

This is not a small step; it is foundational nation-building.

Government messaging and policy direction have consistently reinforced:

  • Financial inclusion
  • Worker protection
  • Long-term income security

And importantly, the intent is clear:
Cambodia is positioning itself to protect its ageing population before demographic pressures peak.

Global Proof … When Value Works, Lives Improve!

To understand what success looks like, Cambodia can draw lessons from proven systems.

In Australia, the superannuation system (US$2.7 trillion industry) has transformed retirement outcomes. Mandatory contributions, disciplined long-term investing, and strong regulation have created one of the largest pension asset pools globally relative to GDP.

The impact is tangible:

  • Retirees enjoy financial independence
  • Dependence on government welfare is reduced
  • Living standards in retirement are significantly higher
  • Pension capital supports national infrastructure and economic growth

In simple terms: Australians don’t just retire, they retire with dignity, stability, and choice.

Similarly, in Hong Kong, the MPF (Mandatory Provident Fund – USD$180 billion) system continuously refined with input from entities like MPF Ratings (HK) has driven a cultural shift toward structured retirement planning. Despite early criticisms, ongoing improvements in transparency, fee control, and performance evaluation have strengthened outcomes.

Most importantly, both systems have achieved something deeper:

Retirement is no longer uncertain … it is planned, measurable, and actively managed.


But Here’s the Reality: Contribution Alone Is Not Enough

Building a pension system is one thing.

Delivering real value is another.

If contributions:

  • Generate weak returns
  • Are eroded by inefficiencies
  • Lack transparency or benchmarking

… then the system risks becoming a savings mechanism without outcomes.

This is where Cambodia must leap forward … not incrementally, but structurally.

The “Money Tree” Framework – A Cambodian Solution

This is exactly where the Money Tree concept, developed through SuperBankRatings (An Andersen Consulting Cambodia Next Generation Research and Rating Platform), becomes very powerful.

The idea is simple but transformative:


Plant Early → Nurture Consistently → Grow Sustainably → Harvest Meaningfully

Applied to retirement:

🌱 Plant

Start contributions early through NSSF, private savings, or investment products.

🌿 Nurture

Ensure funds are:

  • Professionally managed
  • Diversified across asset classes
  • Protected against inflation

 Focus on compounding returns, not just contributions.
🌳 Grow

This is where “value for money” becomes critical.

🍎 Harvest

Convert accumulated wealth into:

  • Sustainable retirement income.
  • Financial independence.
  • Reduced reliance on family or state support.

 Why This Matters for Cambodia’s Future

Cambodia still benefits from a relatively young population. But this advantage will not last forever.

Without strong retirement systems:

  • Future elderly populations may face income insecurity
  • Economic pressure shifts to younger generations
  • National productivity is indirectly affected

With strong, value-driven systems:

  • Long-term domestic capital pools are created
  • Investment markets deepen
  • Financial stability improves


A strong pension system is not just social policy … it is economic strategy.

Government Momentum … And the Opportunity to Leapfrog

The Cambodian government deserves recognition for:

  • Establishing the NSSF pension framework
  • Driving formalization of the workforce
  • Promoting financial inclusion

These are not easy reforms, they require coordination across ministries, regulators, and employers.

But here is Cambodia’s unique advantage:

It does not need to evolve slowly … it can leapfrog.

By embedding:

  • Performance benchmarking
  • Transparent fund management
  • Private sector participation
  • Global “value for money” standards

… Cambodia can build a next-generation pension system from day one.

 The Missing Link: Awareness and Behaviour

Even the best system fails without public understanding.

This is why Money Tree initiatives are critical:

  • Financial literacy
  • Behavioural change
  • Long-term mindset building

Cambodians must begin to see retirement not as a distant concern … but as a current financial strategy.

Final Thought … The Value Equation

At its core, the future of retirement in Cambodia comes down to a simple equation:


Contribution + Performance + Discipline = Real Value

Without performance, contribution is wasted.
Without discipline, performance is meaningless.

And without value? There is no future security.

Cambodia has planted the seeds.
The system is in motion.
The government has laid the foundation.

Now comes the defining phase:

 Will Cambodia grow a forest of financial security … or just a field of unproductive savings?

Because countries like Australia and Hong Kong have already shown what is possible:

 When value is real, retirement is not feared … it is something people can actually look forward to in the Future!

Disclaimer

This article is prepared for informational purposes only and reflects the independent analytical capabilities of Andersen Consulting Cambodia as a fully accredited credit rating agency and provider of financial services research and ratings under its SuperBankRatings product framework.

All ratings and assessments are based on information available at the time of analysis and are subject to ongoing surveillance and review.

Enquiries:

K H Wee-Oon

Chief Research & Rating Officer

Andersen Consulting Cambodia

E: wee-oon.kwanghwee@kh.Andersen.com

Telegram: @KHWeeOon

Renewable Energy In Cambodia: Where ESG Ratings Define True Value

A New Global Reality: Energy Security is No Longer Optional

The ongoing instability in the Middle East has once again exposed a fundamental vulnerability in the global economy, overdependence on fossil fuels and concentrated energy supply chains. Oil price volatility, supply disruptions, and geopolitical risks are forcing governments, investors, and corporations to rethink energy strategies.

Across ASEAN, and particularly in Cambodia, Vietnam, and Laos, this shift is accelerating rapidly. Renewable energy is no longer a “green alternative.” It is becoming a strategic necessity for energy security, economic resilience, and long-term sustainability.

What is Renewable Energy and Why It Matters Now

Renewable energy refers to energy derived from natural sources that are replenished continuously. Unlike fossil fuels, these sources are sustainable, environmentally friendly, and increasingly cost-competitive.

Key Types of Renewable Energy

  • Solar Energy – Harnessing sunlight through photovoltaic (PV) systems
  • Hydropower – Electricity generated from flowing water (a major asset in Laos)
  • Wind Energy – Power from wind turbines (gaining traction in Vietnam)
  • Biomass Energy – Organic material such as agricultural waste
  • Geothermal Energy – Heat extracted from beneath the earth’s surface

Why Renewable Energy is Surging in Cambodia & the Region

1. Energy Security & Independence

Cambodia remains heavily reliant on imported fuel and external energy sources. Renewable energy reduces this dependence and enhances national resilience.

2. Rapid Economic Growth Driving Demand

With GDP growth in the 5–6% range, electricity demand is rising sharply across Cambodia and neighbouring Vietnam and Laos. Renewable energy provides scalable and sustainable capacity expansion. 

3. Cost Competitiveness Has Shifted

Solar and wind are now among the lowest-cost energy sources globally, making them economically viable without heavy subsidies.

4. Regional Advantages

  • Cambodia: Strong solar irradiation potential
  • Laos: Hydropower powerhouse of Southeast Asia
  • Vietnam: Rapid expansion in wind and solar infrastructure  

5. Alignment with ASEAN & Global Climate Goals

Governments are aligning with net-zero commitments, green finance frameworks, and ESG-driven investment mandates.

The Strategic Benefits of Renewable Energy

For Governments

  • Reduced import dependency
  • Improved fiscal stability
  • Enhanced energy security

For Investors

  • Stable, long-term cashflows (via Power Purchase Agreements)
  • ESG-compliant investment opportunities
  • Access to green bonds and sustainable finance

For Corporates

  • Lower long-term energy costs
  • Stronger ESG positioning
  • Enhanced brand and stakeholder trust

The Missing Link: Why ESG Ratings Are Now Critical

As renewable energy projects scale, capital is no longer flowing based on financials alone.

Today’s investors and lenders evaluate projects through three critical lenses:

  • Environmental – Carbon impact, sustainability, climate alignment
  • Social – Community impact, labour practices
  • Governance – Transparency, risk controls, compliance


ESG ratings are becoming the “license to operate” for renewable energy projects.

Without credible ESG assessment:

  • Projects face funding delays
  • Valuations are discounted
  • Investor confidence weakens

With strong ESG credentials:

  • Projects attract premium valuations
  • Access to green financing improves
  • Risk perception significantly reduces

Andersen Consulting Cambodia: Enabling the Energy Transition

Positioned at the intersection of energy, capital markets, and ESG, Andersen Consulting Cambodia is playing a pivotal role in shaping the renewable energy landscape in Cambodia and the broader Indo-China region.


Why Andersen Consulting Cambodia Stands Out

  • Accredited Credit Rating Expertise aligned with regulatory frameworks
  • 25+ years of regional experience spanning Australia, Hong Kong, and Southeast Asia
  • A fully integrated international + local team, combining global standards with local market intelligence

End-to-End Advisory Across the Renewable Energy Lifecycle

Andersen Consulting Cambodia provides a full-suite, investor-grade advisory platform:

  1. ESG Ratings & Credit Assessments
  • ESG scoring aligned with global and regional standards
  • Creditworthiness and risk analysis for energy assets
  • Green bond and sustainable finance readiness 
  1. Investor Readiness & Capital Positioning
  • Preparation of Investor Information Memorandums (IMs)
  • Financial teasers and strategic positioning documents
  • Structuring projects for bankability and investor appeal  
  1. Market Engagement & Capital Raising
  • Market sounding and targeted investor outreach
  • Assessment of indicative interest
  • Strategic engagement with regional and global investors
  1. Transaction Advisory & M&A Support
  • Coordination and management
  • Early-stage structuring for M&A or joint ventures
  • Strategic positioning ahead of formal processes 
  1. Valuation & Due Diligence
  • Business and asset valuation (DCF, comparable multiples)
  • Financial, commercial, and operational due diligence
  • Risk identification and mitigation strategies 
  1. Additional Strategic Services
  • Regulatory advisory (NBC, SERC alignment)
  • ESG compliance preparation and reporting frameworks
  • Post-investment monitoring and rating surveillance
  • Green finance structuring (including bond frameworks)

Why This Matters Now: A Window of Opportunity

Cambodia and its neighbouring markets are at a critical juncture:

  • Energy demand is rising
  • Capital is available but selective
  • ESG is becoming mandatory, not optional

Those who structure, position, and validate their renewable energy assets correctly will attract capital faster, achieve better valuations, and secure long-term strategic advantage.

Final Perspective: From Energy Transition to Energy Leadership

Renewable energy is no longer a future concept; it is the foundation of tomorrow’s economy.

For Cambodia, Vietnam, and Laos, the opportunity is not just to adopt renewable energy but to lead in it.

And in this new paradigm:

  • Energy assets must be bankable
  • Projects must be ESG-compliant
  • Investments must be transparent and structured

Andersen Consulting Cambodia is helping bridge that gap by transforming renewable energy projects into investable, scalable, and globally competitive assets.

Disclaimer

This article is prepared for informational purposes only and reflects the independent analytical capabilities of Andersen Consulting Cambodia as a fully accredited credit rating agency and provider of financial services research and ratings under its SuperBankRatings product framework.

All ratings and assessments are based on information available at the time of analysis and are subject to ongoing surveillance and review.

Enquiries:

K H Wee-Oon

Chief Research & Rating Officer

Andersen Consulting Cambodia

E: wee-oon.kwanghwee@kh.Andersen.com

Telegram: @KHWeeOon

SuperBankRatings: An Andersen Consulting Cambodia’s Research and Rating Platform

Redefining Financial Transparency in Cambodia

SuperBankRatings’, developed under Andersen Consulting Cambodia, represents a next-generation research and rating platform designed to elevate transparency, governance, and performance benchmarking across Cambodia’s financial services sector.

Positioned as Cambodia’s premier independent banking research and rating provider, the platform delivers:

  • Objective, data-driven institutional assessments
  • Comparative benchmarking across the sector
  • Strategic insights for banks, regulators, investors, and consumers

Its core mission is to close the information gap between financial institutions and stakeholders, enabling better decision-making, improved outcomes, and stronger financial systems.


What is SuperBankRatings’? …  A Strategic Intelligence Platform

SuperBankRatings’ is a multi-layered research, analytics, and benchmarking ecosystem.

  1. Core Positioning
  • Independent research & ratings
  • Performance benchmarking platform
  • Financial education and insight provider
  • Market discipline and transparency engine

Unlike credit ratings:

  • Credit ratings – Measure default risk
  • SuperBankRatings – Measures institutional quality, execution capability, governance, and resilience

The SuperBankRatings’ framework applies structured, methodology-driven analysis to deliver rigorous benchmarking, enhanced transparency, and meaningful sector-wide insight. In doing so, it serves as a powerful complement to Andersen Consulting Cambodia’s credit and bond ratings, strengthening market discipline and institutional accountability across the financial services ecosystem. This distinction is particularly critical in emerging markets such as Cambodia, where qualitative institutional strength is often under-analysed.

  1. Methodology … The Engine Behind the Platform

SuperBankRatings’ operates on a comprehensive 11-pillar framework, integrating:

  • Financial strength
  • Governance
  • Risk management
  • Technology & innovation
  • ESG and sustainability

The framework combines:

  • Quantitative metrics
  • Qualitative institutional assessments
  • Peer benchmarking analysis

This methodology is time-tested and globally proven, having shaped:

  • Australia’s superannuation system
  • Hong Kong’s pension ecosystem

Both of which are now considered industry benchmarks.

  1. Products Developed by SuperBankRatings’

(Full Platform Coverage – Based on Official Services & Outputs)

SuperBankRatings’ is not a single product, it is a comprehensive ecosystem of interconnected research, ratings, benchmarking, and engagement tools.

3.1 Core Research & Diagnostic Products

i/ Bank Health Check

A deep-dive institutional diagnostic tool evaluating:

  • Financial performance
  • Strategy and operations
  • Technology infrastructure
  • Risk management and compliance

It provides:

  • Full operational diagnosis
  • Strategic recommendations
  • Forward-looking risk insights

Defined as a tool that evaluates “all aspects of a financial institution’s structure and performance”

ii/  Benchmark Reports

A comparative performance assessment tool enabling financial institution’s to:

  • Measure performance against peers
  • Identify strengths and weaknesses
  • Align with industry standards

Described as an “indispensable tool … to assess market position and performance”

iii/ Form Guides (Signature Product)

A 2-page high-impact institutional snapshot, unique in the financial services’ sector.

Features:

  • Key financial metrics
  • Peer benchmarking
  • Visual dashboards & scorecards
  • Strengths & weaknesses summary
  • Forward-looking indicators

Impact:

  • Simplifies complex banking data
  • Enhances decision-making for investors, regulators, and consumers
  • Improves transparency and governance

Designed to “condense complex data into clear, comparable insights”

3.2 National & Sector Benchmarking Platforms

iv/ SuperBank “Highway” Platform

A flagship digital benchmarking ecosystem providing:

  • Top 10 bank rankings across 3 asset tiers
  • Ratings across all 11 key pillars
  • Peer comparisons across categories

Positioned as Cambodia’s centralised bank ranking and benchmarking hub

v/ SuperPower Index Reports

A multi-report series covering all 11 rating dimensions, including:

  • Financial Strength & Performance Index
  • Governance Index
  • Risk & Liquidity Index
  • ESG & Sustainability Index
  • Technology & Innovation Index

These reports:

  • Rank institutions nationally
  • Provide sector-wide insights
  • Offer strategic recommendations

vi/ MDI & MFI SuperPower Index

Extends the framework beyond banks to:

  • Microfinance institutions (MFIs)
  • Minority depository institutions (MDIs)

Focus:

  • Institutional resilience
  • Funding stability
  • Risk discipline
  • ESG and technology readiness

3.3 Ratings, Awards & Recognition Platform

vii/ Ratings & Awards Framework

A market discipline mechanism that:

  • Recognises top-performing institutions
  • Incentivises better governance and performance
  • Drives competition within the sector

Proven over 20+ years to improve industry standards and transparency

3.4 Research, Insights & Thought Leadership

viii/ Research Products & Publications

SuperBankRatings’ produces:

  • Market analysis reports
  • Sector insights
  • Trend reports
  • Policy-aligned whitepapers

Designed to deliver “in-depth, detailed research and expert opinions”

ix/ News & Industry Thought Leadership

Regular publications covering:

  • ESG trends
  • Digital banking evolution
  • Monetary developments

These insights:

  • Shape market narratives
  • Influence policy thinking
  • Educate stakeholders

3.5 Market Engagement & Ecosystem Development

x/ Events & Industry Engagement

SuperBankRatings’ hosts:

  • Industry forums
  • Workshops
  • Conferences
  • Awards events

Designed to “keep stakeholders informed, inspired, and connected”

xi/ SuperBankRatings’ Endorsed Products

A curated endorsement framework for:

  • Financial products
  • Services aligned with resilience and customer outcomes

Focused on improving “financial resilience and long-term well-being outcomes”

xii/ Financial Education (Money Tree Initiative)

An education platform aimed at:

  • Improving financial literacy
  • Enhancing consumer understanding
  • Supporting long-term wealth outcomes

 3.6 Integrated Platform Summary

SuperBankRatings’ is therefore a multi-layered ecosystem, comprising:

3.6.1 Diagnostic – Health Check

3.6.2 Benchmarking – Benchmark Reports, SuperPower Index

3.6.3 Intelligence – Research Reports, News

3.6.4 Simplification – Form Guides

3.6.5 Market Discipline – Ratings & Awards

3.6.6 Engagement – Events 

3.6.7 Education – Money Tree

3.6.8 Platform – SuperBank Highway

  1. Impact … Shaping Financial Systems (Global to Cambodia)

The methodology behind SuperBankRatings’ has already:

  • Defined benchmarks in Australia and Hong Kong
  • Improved governance and disclosure standards
  • Driven competition and innovation
  • Increased investor confidence

In Cambodia, it is expected to:

  • Enhance transparency across banks, MFIs, and corporates
  • Strengthen regulatory alignment
  • Improve risk management frameworks
  • Attract international investment

Ratings frameworks are proven to “drive transparency, accountability, and stability”

Andersen Consulting Cambodia … Positioned to Lead

Andersen Consulting Cambodia is uniquely positioned due to:

  • Regional expertise across APAC
  • Proven ratings and research pedigree
  • Independence and credibility
  • Integration of ESG, advisory, and ratings

This enables delivery of:

  • Institutional-grade financial intelligence
  • Regulator-aligned frameworks
  • Investor-ready analytics


 The Future … A Transparent Financial Ecosystem

The future of Cambodia’s financial sector will be driven by:

  • Transparency
  • Benchmarking discipline
  • ESG integration
  • Digital transformation
  • Data-driven decision-making

SuperBankRatings’ research and rating platform is positioned at the centre of this evolution.

 A Structural Shift

SuperBankRatings is not just a platform, it is a market-shaping infrastructure.

It transforms:

  • Data – Insight
  • Institutions – Benchmarked entities
  • Markets – Transparent ecosystems

And in doing so, it establishes:

A new standard for financial intelligence, governance, and trust in Cambodia and the wider region.


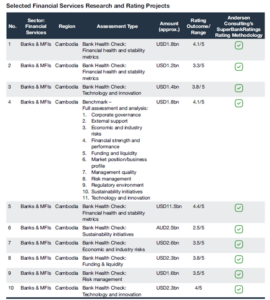
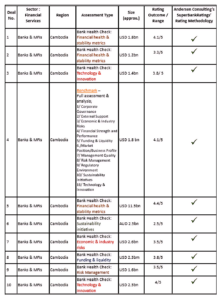
Selected Andersen Consulting Cambodia’s SuperBankRatings’ Financial Services Research & Rating Projects

Disclaimer

This article is prepared for informational purposes only and reflects the independent analytical capabilities of Andersen Consulting Cambodia as a fully accredited credit rating agency and provider of financial services research and ratings under its SuperBankRatings product framework.

All ratings and assessments are based on information available at the time of analysis and are subject to ongoing surveillance and review.

Enquiries:

K H Wee-Oon

Chief Research & Rating Officer

Andersen Consulting Cambodia

E: wee-oon.kwanghwee@kh.Andersen.com

Telegram: @KHWeeOon
What is an ESG Rating? Why Cambodian Businesses Must Prepare Now

An ESG rating evaluates how well an organisation manages risks and opportunities related to environmental, social, and governance factors.

These ratings provide stakeholders with an independent assessment of how responsibly and sustainably an organisation operates.

The three (3) pillars include:

  • Pillar 1 – Environmental

This evaluates how a company manages its environmental footprint and climate impact.

Typical factors include:

  • Carbon emissions and climate strategy
  • Energy usage and renewable energy adoption
  • Waste management and pollution control
  • Natural resource protection
  • Climate resilience and transition planning


  • Pillar 2 – Social

This assesses how an organisation manages relationships with employees, customers, and communities.

Examples include:

  • Labour standards and worker welfare
  • Human rights policies
  • Customer protection and product responsibility
  • Community engagement
  • Diversity and inclusion


  • Pillar 3 – Governance

Governance evaluates the integrity and effectiveness of corporate leadership and decision-making structures.

Key considerations include:

  • Board independence and oversight
  • Transparency and disclosure practices
  • Risk management frameworks
  • Anti-corruption policies
  • Executive accountability

Globally, ESG investing has grown significantly, with sustainable investment strategies managing over USD 30 trillion in assets worldwide, highlighting the increasing importance of ESG data and ratings in financial decision-making.


Why Environmental, Social and Governance (ESG) Standards Are Becoming Essential for Businesses in Cambodia

As Cambodia’s economy matures and integrates more deeply into regional and global capital markets, Environmental, Social and Governance (ESG) standards are rapidly emerging as a critical component of corporate transparency, risk management, and investor confidence.

Across Asia and globally, ESG is no longer viewed as a voluntary corporate responsibility initiative. It is increasingly becoming a regulatory expectation, a financing prerequisite, and a strategic management tool for corporations, banks, and financial institutions.

Cambodia is now entering this phase of transition.


ESG Compliance and Disclosure in Cambodia

Cambodia has begun developing a regulatory framework for ESG and sustainable finance.

One of the most significant developments is the ESG Disclosure Prakas issued by the Securities and Exchange Regulator of Cambodia (SERC).

Under this regulation:

  • Companies listed on the Cambodia Securities Exchange (CSX) will be required to publish ESG disclosures.
  • Mandatory reporting includes environmental and social risks, impacts, and mitigation strategies.
  • Companies must report key sustainability metrics such as greenhouse gas emissions and social impact policies.

These disclosures are expected to become effective from May 2026, although voluntary reporting is encouraged in advance.

The Cambodian government is also working with international partners to expand sustainable finance frameworks, including ESG guidelines, climate-related financing mechanisms, and green investment strategies.

Why ESG Ratings Are Becoming Necessary in Cambodia

Several structural forces are driving the rapid adoption of ESG standards in the Kingdom.

  1. Access to International Capital

International investors increasingly require ESG disclosures before committing capital.

Without ESG reporting, Cambodian companies may face challenges accessing:

  • International bond markets
  • Sustainable investment funds
  • Development finance institutions
  1. Growth of Green and Sustainable Bonds

Cambodia is actively promoting green bond issuance to finance climate-related projects such as renewable energy, sustainable infrastructure, and energy efficiency.

Programs supported by regulators and development institutions aim to accelerate sustainable bond issuance and align Cambodian issuers with international ESG standards.

  1. Climate and Environmental Risks

Cambodia faces increasing exposure to climate risks such as flooding and drought.

These risks can significantly affect economic growth and financial stability, making ESG risk management an important tool for financial institutions and corporates.

  1. ASEAN Sustainable Finance Integration

Cambodia is part of the broader ASEAN sustainable finance ecosystem.

Regional initiatives such as the ASEAN Sustainable Finance Taxonomy and ESG disclosure frameworks are designed to standardize sustainability reporting across Southeast Asia and improve transparency for investors.


Which Entities Are Affected by ESG Compliance?

Currently, ESG compliance requirements are primarily focused on capital markets participants, but the scope will expand over time.

  • Entities Currently Affected

– Listed Companies

Companies listed on the Cambodia Securities Exchange must begin ESG disclosures under the SERC framework.

– Bond Issuers

Corporations issuing green, social, or sustainability bonds must demonstrate ESG compliance and reporting to investors.

– Banks and Financial Institutions

Financial institutions are increasingly integrating ESG risk into lending and investment decisions through sustainable finance principles.

– Large Corporations and Multinationals

Companies operating within international supply chains must comply with ESG expectations imposed by global partners and investors.

  • Entities Likely to Be Affected in the Future

Over the next 3–5 years, ESG requirements are expected to extend to:

  • Commercial banks
  • Microfinance institutions
  • Insurance companies
  • State-owned enterprises
  • Infrastructure developers
  • Property developers
  • Energy and mining companies
  • Export-oriented manufacturers
  • Large family-owned conglomerates

In addition, SMEs participating in international supply chains will increasingly need to disclose ESG information to meet procurement and financing requirements.

The Role of Regulators and Stakeholders

Several Cambodian regulators and institutions are involved in advancing ESG and sustainable finance.

Key stakeholders include:

Securities and Exchange Regulator of Cambodia (SERC)

  • ESG disclosure regulations
  • Sustainable bond frameworks
  • Capital market transparency

National Bank of Cambodia (NBC)

  • Sustainable banking initiatives
  • Climate finance development
  • Financial sector risk management

Ministry of Economy and Finance (MEF)

  • Fiscal policy and sovereign sustainability strategies

Ministry of Environment (MoE)

  • Environmental regulation and climate policy

International Development Institutions

Partners supporting Cambodia’s ESG transition include:

  • International Finance Corporation (IFC)
  • Asian Development Bank (ADB)
  • World Bank
  • UN agencies

These institutions help develop policy frameworks, capacity building, and sustainable finance programs in Cambodia.

Why Preparation for ESG Matters Now

Although ESG reporting requirements are still evolving in Cambodia, early preparation is essential.

Companies that begin ESG preparation early will benefit from:

  • Improved investor credibility
  • Easier access to financing
  • Stronger corporate governance structures
  • Reduced regulatory risks
  • Enhanced brand reputation

Conversely, companies that delay preparation may face higher costs and greater regulatory pressure in the future.

Andersen Consulting Cambodia: Spearheading ESG Ratings and Compliance

As Cambodia’s financial markets develop, independent ESG assessment and ratings will play a crucial role in strengthening transparency and investor confidence.

Andersen Consulting Cambodia is at the forefront of this development as an accredited Credit Rating Agency (CRA) in the Kingdom.

With a combined international and local team, and 25+ years-experience across the region, Andersen brings extensive expertise in:

  • Credit and bond ratings
  • Sustainable finance analysis
  • ESG risk evaluation
  • Corporate governance assessments
  • Financial sector research

By integrating ESG analysis within credit and financial ratings frameworks, Andersen helps:

  • Corporates prepare for ESG disclosures
  • Financial institutions manage sustainability risks
  • Bond issuers meet international investor expectations
  • Regulators strengthen market transparency

This capability is particularly important as Cambodia moves toward a more sophisticated capital market ecosystem aligned with ASEAN and international standards.

The Strategic Importance of ESG for Cambodia

The rise of ESG is not simply a regulatory trend, it represents a structural transformation in how economies and financial systems operate.

For Cambodia, ESG integration will help:

  • Strengthen financial sector resilience
  • Attract long-term international investment
  • Support sustainable economic growth
  • Improve environmental protection and climate resilience
  • Enhance corporate governance and transparency

Ultimately, ESG ratings and compliance are becoming a foundational component of Cambodia’s financial and economic modernization

Disclaimer

This article is prepared for informational purposes only and reflects the independent analytical capabilities of Andersen Consulting Cambodia as a fully accredited credit rating agency and provider of financial services research and ratings under its SuperBankRatings product framework.

All ratings and assessments are based on information available at the time of analysis and are subject to ongoing surveillance and review.

Enquiries:

K H Wee-Oon

Chief Research & Rating Officer

Andersen Consulting Cambodia

E: wee-oon.kwanghwee@kh.Andersen.com

Telegram: @KHWeeOon

What Does a Credit Rating Actually Measure in Cambodia?

As Cambodia’s capital markets mature, credit ratings are often discussed, but rarely explained in practical terms. Too often, they are reduced to a single letter grade or perceived as a regulatory checkbox. In reality, a credit rating is a structured diagnostic of institutional strength and risk, designed to answer one fundamental question: how resilient is this issuer across an economic cycle in Cambodia’s real operating environment?

At Andersen Consulting Cambodia, the objective is not merely to be accredited, but to explain clearly what a Credit Rating Agency (CRA) actually measures in practice and why it matters for issuers, investors, and regulators alike.

In Cambodia, a credit rating is built on five core analytical pillars.

  1. Financial Strength

This pillar assesses whether an institution can absorb stress and continue operating. Analysts examine capital adequacy, asset quality, earnings stability, leverage, and balance sheet resilience.

In a Cambodian context where banks, corporates, and project vehicles often operate in a fast-growing but still-evolving market, financial strength is about durability, not just recent profitability. Strong ratings reward institutions that demonstrate conservative capitalization, disciplined growth, and transparent financial reporting aligned with regulatory expectations.

  1. Governance

Governance evaluates who makes decisions, how those decisions are made, and whether accountability exists.

This includes board independence, management competence, ownership structure, internal controls, and disclosure standards. In Cambodia’s transition from relationship-based finance toward institutional capital markets, governance quality is often the key differentiator between entities that can access long-term funding and those that cannot.

A credit rating directly reflects whether governance structures reduce key-person risk, conflicts of interest, and operational opacity.

  1. Risk Management

Risk management measures how well an institution identifies, monitors, and mitigates financial and non-financial risks.

This includes credit risk, concentration risk, market risk, operational risk, and compliance risk. For Cambodian issuers, particularly those expanding into bonds, project finance, or structured instruments, ratings assess whether risk frameworks are proactive or merely reactive.

A robust risk management systems signal institutional maturity and are central to rating stability over time.

  1. Liquidity

Liquidity answers a simple but critical question;

“ Can the issuer meet its obligations when they fall due under both normal and stressed conditions?

 Analysts examine funding sources, maturity mismatches, access to contingent liquidity, and reliance on short-term or concentrated funding. In Cambodia, where capital markets are still developing and refinancing risk can be acute, liquidity strength is often a decisive rating factor.

Strong liquidity profiles support longer tenors, better pricing, and investor confidence.

  1. Sustainability

Sustainability goes beyond ESG labels. It evaluates whether an institution’s business model is viable over the long term, considering environmental, social, regulatory, and structural factors.

For Cambodia, this includes exposure to sectoral concentration, regulatory evolution, climate and transition risks, and alignment with national development priorities led by the National Bank of Cambodia.

Sustainability anchors ratings in future resilience, not just historical performance.

 From Accreditation to Application

A credit rating is not a marketing exercise, nor a subjective opinion. It is a disciplined, rules-based assessment that translates complex institutional realities into a transparent risk signal, one that investors, regulators, and boards can rely on.

As Cambodia integrates more deeply into regional and global capital markets, credible ratings become part of the country’s financial infrastructure, alongside exchanges, regulators, and disclosure standards.

 A credit rating is not an opinion. It is a disciplined, rules-based risk signal. That alignment when embedded at scale, turns transparency into trust, and trust into the foundation of Cambodia’s next Super Capital Market.

Andersen Consulting Cambodia Deal List

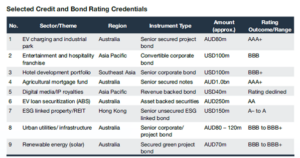
Credit Rating Services – The firm is accredited as a CRA by the Securities and Exchange Regulator of Cambodia. Selected deals are provided in the table below.

 Supporting transparent capital pricing, investor confidence, and market discipline in Cambodia and the region.


 Selected Credit and Bond Rating Credentials

Beyond regulated credit and bond ratings, Andersen Consulting Cambodia deploys a specialized financial services rating and research framework known as ‘SuperBankRatings’. Designed specifically to evaluate and assess Cambodia’s banking and microfinance sector, this framework applies structured, methodology-driven analysis to deliver rigorous benchmarking, enhanced transparency, and meaningful sector-wide insight. In doing so, it serves as a powerful complement to formal credit ratings, strengthening market discipline and institutional accountability across the financial services ecosystem.

The framework evaluates financial strength, governance, risk management, innovation, and value delivered to customers. 

Key Assessment Dimensions

The SuperBankRatings framework assesses:

  • Customer service and digital banking capability
  • Financial strength (capital adequacy, asset quality, profitability)
  • Corporate governance and transparency
  • Innovation and product relevance
  • Market position and geographic reach
  • Risk management and regulatory compliance
  • Financial inclusion and social responsibility
  • Sustainability and ESG initiatives

Assessments are based on publicly available data and information sourced directly from institutions

Selected Andersen Consulting Cambodia’s SuperBankRatings’ Financial Services Research & Rating Projects

Disclaimer

This article is prepared for informational purposes only and reflects the independent analytical capabilities of Andersen Consulting Cambodia as a fully accredited credit rating agency and provider of financial services research and ratings under its SuperBankRatings product framework.

All ratings and assessments are based on information available at the time of analysis and are subject to ongoing surveillance and review.

Enquiries:

K H Wee-Oon

Chief Research & Rating Officer

Andersen Consulting Cambodia

E: wee-oon.kwanghwee@kh.andersen.com

Telegram: @KHWeeOon

Institutionalising Trust: Why Credit & Bond Ratings Matter for Cambodia’s Financial Future

The article explores:

  • The strategic role of credit and bond ratings in strengthening transparency, risk pricing, and investor confidence as Cambodia’s financial system transitions from high growth to institutional maturity.
  • Why independent credit ratings are essential to the success of Cambodia’s Financial Sector Development Strategy 2025–2030, particularly in deepening capital markets and improving financial stability.
  • How the accreditation of Andersen Consulting Cambodia as a licensed Credit Rating Agency represents a structural shift away from relationship-based credit assessment toward independent, rules-based risk evaluation.
  • The importance of independence, non-conflict, and governance discipline under Cambodia’s CRA Prakas in ensuring ratings credibility and market trust.
  • How Andersen Consulting Cambodia positions itself as a long-term institutional advisor, combining global methodologies, local execution, licensed ratings, and governance frameworks to support Cambodia’s evolution into a competitive regional financial hub.
  •  

C redit & Bond Ratings in Cambodia: A Cornerstone for Financial Maturity and Regional Competitiveness

Cambodia’s financial sector is entering a decisive phase of institutional maturity. Over the past two decades, the Kingdom has built a resilient banking and microfinance system, expanded capital market infrastructure, and progressively aligned its regulatory framework with international standards. The launch of Cambodia’s Financial Sector Development Strategy (FSDS) 2025–2030, driven by the National Bank of Cambodia (NBC), marks a clear strategic intent: to transition from rapid growth towards stability, transparency, and long-term sustainability.

Within this context, credit and bond ratings are no longer optional. They are a foundational requirement for Cambodia’s ambition to evolve into a competitive regional financial hub and to attract long-term domestic and international capital.

Why Credit & Bond Ratings Matter in a Developing Financial Market

Credit and bond ratings serve a fundamental economic function: They provide an independent, standardised assessment of credit risk. In markets where financial intermediation has historically relied on relationship-based lending, collateral-heavy structures, or implicit guarantees, ratings introduce discipline, comparability, and accountability.

For Cambodia, the importance of ratings can be summarised across several critical dimensions:

  1. Enhancing Market Transparency and Investor Confidence

Investors; Particularly institutional investors such as pension funds, insurers, development finance institutions, and sovereign wealth funds require objective risk benchmarks. Credit ratings translate complex financial, operational, and governance data into a transparent and comparable signal of creditworthiness.

Without credible ratings, capital markets remain shallow, pricing remains opaque, and investor participation remains limited to those with local knowledge or relationship access. With positive ratings, Cambodia becomes legible to global capital.

  1. Supporting the Development of Domestic Bond Markets

A functioning bond market cannot exist without ratings. Issuers require ratings to price risk efficiently, while investors require them to assess suitability relative to mandates and risk appetite.

Credit ratings enable longer tenors, diversified funding sources, and lower cost of capital for Cambodia’s:

  • Corporate bond issuers,
  • Financial institutions,
  • Infrastructure projects, and
  • Quasi-sovereign and public-sector entities.

This directly supports the NBC’s objective under the FSDS 2025–2030 to deepen capital markets and reduce over-reliance on bank lending.

  1. Improving Capital Allocation and Financial Stability

Ratings promote risk-sensitive capital allocation. Stronger credits are rewarded with lower funding costs, while weaker credits are incentivised to improve governance, disclosure, and financial discipline.

From a systemic perspective, this reduces:

  • Mispricing of risk
  • Excessive concentration
  • Hidden vulnerabilities within the financial system

In doing so, ratings enhance macro-prudential oversight, a key pillar of Cambodia’s financial sector strategy.

  1. Accelerating Governance and Disclosure Standards

To obtain and maintain a credible rating, issuers must improve:

  • Financial reporting quality
  • Internal controls
  • Risk management frameworks
  • Board oversight and transparency

This creates a virtuous cycle where ratings act not merely as an assessment tool, but as a catalyst for institutional improvement across the economy.

Credit Ratings and Cambodia’s Financial Sector Development Strategy 2025–2030

The FSDS 2025–2030 explicitly prioritises:

  • Financial stability,
  • Market deepening,
  • Transparency and governance, and
  • Regional and international integration.

Independent credit ratings directly support all four objectives.

As Cambodia integrates more deeply with ASEAN financial markets and global capital flows, ratings become the common language that allows Cambodian institutions to be compared, understood, and trusted alongside regional peers in Vietnam, Malaysia, and Singapore.

In short, no modern financial hub operates without a credible domestic credit rating ecosystem.

A Structural Shift: Andersen Consulting Cambodia’s Credit Rating Agency Accreditation

Andersen Consulting Cambodia’s  accreditation as a Credit Rating Agency (CRA) represents a structural inflection point in Cambodia’s financial ecosystem.

It signals a transition from:

  • Relationship-based credit assessment
  • Informal or implicit risk judgments

towards:

  • Institutionalised, independent, and rules-based risk evaluation

This shift aligns precisely with the Prakas on Accreditation of Credit Rating Agencies, which emphasises independence, absence of conflicts of interest, robust governance, and methodological integrity.

Independence and Non-Conflict as a Core Principle

Under the Prakas framework, a CRA must operate with:

  • Full analytical independence
  • Clear separation between rating activities and advisory or transactional services
  • Strong internal controls to prevent conflicts of interest

Andersen Consulting Cambodia’s CRA accreditation reflects adherence to these principles. Its ratings function is structurally independent, methodology-driven, and governed by strict compliance with regulatory and ethical standards.

This independence is critical. Without it, ratings lose credibility. With it, ratings become trusted public goods that benefit issuers, investors, regulators, and the broader economy.

Andersen Consulting Cambodia: Beyond Transactions, Towards Institutional Trust

Andersen Consulting Cambodia (formerly VDB-Loi) is positioning itself not as a transaction-driven consultant, but as a long-term institutional advisor aligned with Cambodia’s national development trajectory. 

This positioning is built on the integration of four core pillars:

  1. Global Andersen Consulting Methodologies

As part of the global Andersen platform, Andersen Consulting Cambodia applies:

  • International credit rating frameworks,
  • Standardised analytical methodologies,
  • Globally benchmarked risk models.

This ensures consistency, credibility, and international comparability essential for attracting cross-border capital.

  1. Deep Cambodia Execution Capabilities

Global standards alone are insufficient without local understanding. Andersen Consulting Cambodia brings over 25 years of regional and international ratings, research, and analytical experience, combining global best practice with deep local market understanding to strengthen transparency, investor confidence, and market discipline across Cambodia’s financial services sector, including:

  • Deep regulatory knowledge,
  • Local market insight,
  • Cultural and institutional fluency.

This allows ratings and advisory outputs to be globally credible yet locally grounded.

  1. Credit Ratings and Financial Analytics

The CRA accreditation enables Andersen Consulting Cambodia to provide:

  • Independent credit ratings,
  • Financial strength assessments,
  • Risk analytics aligned with regulatory expectations.

These capabilities directly support capital market development, banking supervision, and institutional decision-making.

 Governance and Transparency Frameworks

Beyond ratings, Andersen Consulting Cambodia works with institutions to strengthen:

  • Governance structures,
  • Risk management systems,
  • Transparency and disclosure practices.

This reinforces the view of ratings as part of a broader institution-building agenda, not merely a compliance exercise.

H elping Cambodia Transition from Growth to Maturity

Cambodia’s financial system has successfully navigated a high-growth phase. The challenge ahead is different: managing scale, complexity, and systemic risk while remaining competitive and inclusive.

Independent credit and bond ratings are essential to this transition.

They:

  • Anchor market discipline
  • Support regulatory oversight
  • Enable sustainable capital formation

By combining global methodologies, local execution, licensed rating authority, and governance expertise, Andersen Consulting Cambodia aims to help Cambodian institutions move confidently from growth to maturity.

In doing so, it contributes not only to individual issuers or transactions, but to the long-term credibility and resilience of Cambodia’s financial ecosystem, a prerequisite for the Kingdom’s emergence as a respected regional financial hub.


For more information, please contact QnA@SuperBankRatings.com

Plant Your Money Tree Today: Grow Wealth, Secure Retirement & Empower Generations

The article explores:

  • Why Starting Early Matters: Building financial education, saving, investing, and retirement planning now lays the foundation for lifelong security.
  • The Money Tree – Your Symbol of Growth: How SuperBankRatings’ Money Tree program mirrors and supports real-world wealth building and financial literacy.
  • Future-Ready Retirement – Flexibility is Power: What modern retirement planning from flexible income strategies to shifting economic landscapes can teach and prepare for the future.

A Changing Cambodia, A Growing Opportunity

Cambodia is moving into a new financial era. Over the past decade, the country has experienced steady economic growth, an expanding middle class, and increasing participation in global trade. More Cambodians are working in formal jobs, earning stable salaries, and using digital banking services. Yet at the same time, financial literacy levels remain low, household debt is rising, and retirement savings are still a distant thought for many.

In this fast-changing landscape, one question becomes urgent: How do we make money work for us, not just today, but for our entire lifetime and for the generations after us?

The answer lies in two powerful, interconnected tools: financial education and retirement planning. With these, every Cambodian can learn how to plant their own “Money Tree”, a symbol of long-term wealth, security, and legacy.

Why Starting Early Matters: Seeds of Wealth and Wisdom

Wealth is not created overnight. Just like a mango tree or coconut palm, it grows slowly but surely with care, patience, and discipline. Many people mistakenly believe that wealth building is only for the rich or for those working abroad. The truth is: ” … Anyone, regardless of income, can begin planting seeds today… “

The Power of Time and Compounding

Financial education teaches us that starting small but starting early is more valuable than waiting until we are older. For example, if you save only USD $30 per month from age 25 and invest it in a low-risk product that earns 5% per year, by the time you are 60, your savings will grow to over $27,000. But if you wait until age 40 to begin saving the same amount, you’ll only have about $10,000 by 60.

Time is the secret ingredient. The earlier you start, the larger your “Money Tree” becomes.

Financial Education as Protection

In Cambodia, scams, predatory lending, and get-rich-quick promises are common.

A solid foundation in financial literacy acts like a shield.

It helps you ask the right questions:

Is this investment real?

What are the risks?

What are the fees?

Without this shield, many hard-earned salaries are lost in gambling, speculation, or unsustainable debts.

Breaking the Cycle of Poverty

Education is not just for the present it creates ripple effects across generations. Parents who understand how to budget, save, and invest pass on not just money, but wisdom. Children grow up with healthier financial habits, ensuring a stronger financial foundation for Cambodia’s future workforce. 

The Money Tree: A Living Symbol of Growth

SuperBankRatings’ Money Tree program is more than just a teaching tool; it is a metaphor everyone  understands. In our culture, trees represent life, growth, and abundance. The Money Tree program takes that symbolism and turns it into action.

What is the Money Tree Program?

Developed by SuperBankRatings, the Money Tree is an interactive financial education program that teaches citizens young and old, the core pillars of money management:

  • Earning: Building stable income streams.
  • Saving: Developing the discipline to set aside money.
  • Investing: Growing wealth with careful choices.
  • Retirement Planning: Preparing for life beyond work.
  • Protection: Avoiding scams and financial pitfalls.

By gamifying financial literacy and breaking down complex concepts into everyday language, the program directly supports Cambodia’s National Financial Inclusion Strategy (NFIS), a government-endorsed effort to bring quality financial services and education to the entire population.

Why the Money Tree Matters for Cambodia

In a nation where agriculture is part of our roots, the metaphor resonates deeply. Just as a farmer plants crops for future harvest, financial education is planting seeds of prosperity. The earlier Cambodians engage with these tools, the faster they can grow sustainable financial independence.

And just like a tree that bears fruit year after year, financial education creates a legacy that benefits not just one generation, but many.

Retirement That Moves With You: Lessons From Abroad

When Cambodians think of retirement, many still imagine depending on their children, selling land, or relying on small informal savings. But the world is changing. Retirement today must be flexible, reliable, and sustainable.

Lessons From Hong Kong’s MPF (Pension) Ratings

Recent research from MPF Ratings in Hong Kong offers insights everyone can learn from. Their report emphasises the importance of:

  • Flexible income streams: Retirees should choose how they receive money monthly, quarterly, or annually.
  • Low-cost structures: Fees eat into retirement funds, so transparency is essential.
  • Simple withdrawal systems: Retirees should access money without paperwork nightmares or hidden penalties.

For example, Hong Kong’s Sun Life MPF Income Fund lets retirees set predictable income patterns, creating stability without stress. Cambodia can adapt similar lessons by pushing banks, insurers, and pension providers to create low-fee, flexible retirement products that suit both rural and urban workers.

Cambodia’s Own Pension Scheme

Cambodia has already taken a historic step. Since October 1, 2022, the government’s private-sector pension scheme allows workers to retire with predictable benefits. Employees and employers contribute regularly, and at age 60, retirees receive a pension based on their salary. If the contributor dies prematurely, family members receive support.

This is a milestone. For the first time, Cambodia is creating a system where retirees won’t have to depend solely on their children. But to make it successful, citizens must actively understand, engage, and complement it with their own private savings and investments. 

Cambodia’s Advantage: Why Now Is the Best Time

While challenges remain, Cambodia holds unique advantages for those who act now.

Low Cost of Living

Cambodia remains one of Southeast Asia’s most affordable countries. Retiring here costs far less than in Thailand, Vietnam, or Malaysia. Housing, healthcare, and food remain accessible, meaning modest savings go much further.

Government Incentives

Through the Council for the Development of Cambodia (CDC), investors and businesses receive tax incentives, corporate tax breaks, and sector-specific benefits. This environment encourages the growth of financial services, making wealth-management products more available and affordable.

Education and Human Capital

Institutions such as CamEd Business School, accredited by CFA Institute and ACCA, are preparing a new generation of finance professionals. These future leaders will strengthen Cambodia’s financial literacy and product offerings, improving wealth management options nationwide.

Digital Transformation

Mobile banking, QR code payments, and digital wallets are expanding rapidly in Cambodia. This digital revolution makes saving, investing, and accessing pensions easier, even for those outside major cities.

Additional Supportive Strategies for Citizens

Here are actionable steps every Cambodian can take today:

  1. Start a Retirement Account Early
    Even if the contributions are small, consistency builds long-term wealth.
  2. Diversify Savings
    Don’t rely only on land or gold. Explore safe savings plans, pensions, and mutual funds where available.
  3. Leverage Government Schemes
    Register for the national pension and stay informed about new government programs supporting retirement.
  4. Invest in Financial Education
    Participate in initiatives like the Money Tree program, attend workshops, and use free online resources.
  5. Teach the Next Generation
    Pass on financial knowledge to children. Teaching them how to manage money is more powerful than giving them money alone.

Planting a Legacy: Why It Matters for Families and Generations

In Cambodian culture, family is everything. Yet too often, financial struggles pass from parents to children. Breaking that cycle requires vision.

By embracing financial education and retirement planning:

  • Parents become independent in old age, reducing the financial pressure on their children.
  • Children inherit not just assets, but strong financial habits.
  • Communities benefit from greater stability and resilience, reducing reliance on debt and informal lending.

“ … Your “Money Tree” Does not only Feed you, it Shades and Shelters your family for decades… “

he Time to Act is Now

The journey to wealth and retirement security begins not with money, but with knowledge.

“ … Financial education is the seed. Wealth management is the soil. Retirement planning is the harvest … “

Cambodia is at a turning point. With government pensions, financial inclusion strategies, and private programs like SuperBankRatings’ Money Tree, the tools are finally available. The question is: will you use them?

If you start today, even with small steps, you’re not just saving money, you are building a future of dignity, independence, and legacy.

So, plant your Money Tree now. Water it with discipline, sunlight it with education, and protect it with good decisions.

The sooner you begin, the greater your harvest will be. And when that day comes, you won’t just look back with relief, you will look forward with pride, knowing your children and grandchildren are growing in the shade of the tree you planted.

For more information, please contact QnA@SuperBankRatings.com

SuperBankRatings: The TripAdvisor of Banking

The article explores:

  • Applying the TripAdvisor model to banking: How SuperBankRatings ‘ enables clear, like-for-like comparisons of banks and products from a customer and market perspective, demystifying complex banking choices.

  • Data-driven, customer-centric ratings: How large volumes of banking data are filtered into simple, meaningful star ratings that reflect real customer experience, performance, and service quality, not just price.

    Transparency and trust as competitive advantages: How independent, consistent, and transparent ratings build credibility, improve market confidence, and help banks understand where they truly stand versus competitors.

J ust think how hard it was to book vacations before TripAdvisor. So many hotels. So many bad ones. So much to comprehend. This frustration led Stephen Kaufer to start TripAdvisor. Today TripAdvisor is the leading rating service for vacations, trusted by travellers and businesses alike. It has 8 million venues reviewed from over 8 billion site-visits. It allows informed decisions. It is data driven. TripAdvisor focuses on the Customer and is transparent. Banking may seem unrelated to vacations but the same challenges for travel applies to banks. There is no clear basis for comparisons of products and services. This is what SuperBankRatings’ will solve. Rating banks from a customer and market perspective to enable like for like comparisons. To reveal what 5 stars looks like.

The importance of informed decisions

No-one travels without researching hotels. Things like cost, location, quality are always important, as are the dining options, the pool and entertainment choices. TripAdvisor’s ratings allow travellers to compare like for like hotels, across several aspects. Vacations can be booked with confidence.

Banking decisions deserve the same research. But there is no BankAdvisor. Unlike hotels, banks are complicated. Their products and services are confusing. However, there are similarities. Branch locations and customer service remain important. Quality and specialty are critical. A bank which specialises in business banking is not always best for someone needing consumer banking.

SuperBankRatings’ allows customers to make informed decisions by seeing how different banks compare on the same factor. Where they differ while keeping other factors the same. There is more to a mortgage than the interest rate, as there is more to a hotel than price. SuperBankRatings’ enables the market to be better informed when choosing between competing offers.

Data driven, Insight focused

TripAdvisor integrates data from open, private, interactive and closed sources. Customers leave reviews and businesses can reply. Beyond the user and hotel there are subscribers, partners, advertisers and travel agents. TripAdvisor delivers the most comprehensive data platform for the travel industry.

Banking generates mountains of data. Everything is measured and counted. All sorts of organisations track the data and results. The challenge becomes filtering out the noise. Facts like biggest bank, by assets, customers, loans, market share, growth are only useful with context. What does it mean when a bank is said to be over-exposed, or facing a customer concentration risk?

SuperBankRatings’ simplifies this deluge of data. The analysis converts something which sounds impenetrable into something useful. A simple scale to show how several factors come together to deliver a service or product to the market which is either fantastic or not. The analysis shows what options exist, and sometimes challenges assumptions the market has about what “good” means.

One surprise about being data driven is that 5 stars from TripAdvisor has the same value across different types of hotels. SuperBankRatings’ does the same thing. Once a rating is established it applies across all respective class.

The Customer is King

TripAdvisor places the customer at the centre of its rating by giving them a voice. The customer’s experience drives the ratings as much as formal reviews. The customer can talk to the hotel, avoiding the marketing and PR departments. Hotels can hear what customers really experience. Low ratings have value because it shows where improvement is needed, or what the problem really is.

The same applies for Banks. SuperBankRatings’ can show whether a new Customer Service program is having impact. The ratings will measure how complaints handling and volume is changing, or if market share is increasing through new customer acquisition drives. A profitable bank has happy customers. Happy customers have a voice and have access to the banking they need. Having an independent rating gives you the credibility to speak directly to the market. It is the trusted voice in a crowded room, people are more likely to listen.

T ripAdvisor is number 1 because its ratings mean something. A rating only changes when effort is made to improve, or a business gives up. The inputs are known even if the methodology is secret. As a result, a 4 star rating in one place equals 4 stars somewhere else. The ratings can be trusted.

SuperBankRatings’ is open about what factors are considered important. Open about how performance against those factors can be changed but the methodology remains the same. Transparency comes from being open about findings which correspond to what the market and customers see themselves. SuperBankRatings’ currency is their Research & Ratings, Credibility and Independence are their biggest assets. This reputation is built on Transparency and Fairness with all market partners.

Soon Cambodia’s banking market will say “remember what it was like before SuperBankRatings’?”. Those old days will be like booking a vacation before TripAdvisor. Confusing, complicated, frustrating. With SuperBankRatings’, the market will have confidence they’re making informed decisions. Ratings will be data driven to show how things change relative to important inputs and variables. Banks will be able to hear from their customers because the customers will better understand the banks. Most important is SuperBankRatings’ will bring transparency by comparing the competitive offers available in market. Show banks how they can improve or how well they are doing versus the competition. When SuperBankRatings’ says something is 5 Star just like TripAdvisor, it will mean excellence!

Article by Ishmael Jappie-Giles 

For more information, please contact QnA@SuperBankRatings.com

From Horse Racing to Banking: How Form Guides Improve Financial Decision-Making

The article explores:

  • How a simplified, two-page Form Guide transforms complex banking data into clear, comparable insights helping consumers, regulators, investors, and banks make better, more informed decisions.
  • Why transparency, benchmarking, and evidence-based assessment are essential in fast-growing markets like Cambodia and ASEAN, where financial products look similar but vary dramatically in strength, risk, and long-term stability.
  • How the Form Guide elevates financial literacy, strengthens trust, and improves governance across the banking sector, ultimately supporting a more resilient, competitive, and consumer-focused financial system.

Anyone who has ever spent a day at the races knows the value of a good form guide. It condenses hundreds of data points; track history, jockey performance, weights, barriers, timings all into a short, readable profile that lets punters assess strengths, weaknesses, and the likelihood of a favourable outcome. In a world of uncertainty, the form guide becomes a decision-maker’s best friend.

Now imagine having the same clarity, structure, and insight when assessing banks, financial products, bonds, or retirement funds. That is exactly what the SuperBankRatings Form Guide aims to deliver: a concise, two-page, data-driven snapshot of a bank’s performance, strength, and reliability. Much like its racing counterpart, it offers an objective overview that helps individuals, businesses, and institutions make better, more confident financial decisions.

In an environment where consumers are bombarded with information, and misinformation, a clear, comparable, and trustworthy research is no longer optional. It is essential. And that is where a well-constructed financial form guide becomes not only helpful, but transformative.

The Power of a Form Guide: A Familiar Concept Applied to Finance

The genius of a form guide lies in its simplicity. It compresses reams of complex data into a structured, easy-to-read summary that allows users to quickly compare competing options.

This same philosophy underpins the SuperBankRatings Form Guide.

Just as punters analyse competing horses before placing their bets, financial consumers should be able to evaluate banks on key dimensions; financial strength, liquidity, asset quality, risk management, operational efficiency, and customer value. And just as a racing form guide gives all the necessary insights without burying the reader in jargon, the SuperBankRatings Form Guide distils a wide universe of data into a highly digestible, visually intuitive format.

The goal is not to oversimplify. The goal is to simplify clarity, enabling readers to navigate complex financial information with confidence and precision.

What the SuperBankRatings Form Guide Offers (in Just Two Pages)

The SuperBankRatings approach is deliberately concise: a two-page summary designed for quick but meaningful assessment. Behind those two pages sits a substantial amount of analytic work, drawing inspiration from both bank rating methodologies and retirement fund scorecards.

The Form Guide typically incorporates:

  1. Key Financial Metrics and Strength Indicators
  • Asset growth
  • Capital adequacy
  • Funding stability
  • Loan book quality
  • Liquidity buffers
  • Profitability trends

These indicators help users answer critical questions: Is this bank strong? Stable? Growing responsibly? 

  1. Benchmarking Against Peers

Standing alone, numbers have limited meaning. A 15% growth rate sounds impressive until you learn the industry grew at 22%. The Form Guide therefore shows where a bank stands among its peers, making comparisons easier, fairer, and more meaningful.

  1. Visual Dashboards and Scorecards

Charts, heat maps, grids, and summary indicators reduce cognitive load and enable instant insight, an approach which uses ratings, colours, and indicators to summarise for example retirement fund performance across multiple factors.

  1. Strengths and Weaknesses

A concise narrative or bullet-point summary highlights:

  • What the bank does particularly well
  • Where the bank is underperforming
  • Recent improvements or warning signs
  • Areas that require monitoring

This helps readers form a holistic view quickly, much like noting a horse’s late-race acceleration or favourable barrier position.

  1. A Neutral, Evidence-Based Perspective

The Form Guide does not sell, promote, or defend any institution. It presents evidence and structured analysis giving readers the facts they need without promotional language or marketing spin.

Why Ratings and Form Guides Matter: Empowering Better Decisions

In a financial world full of complex choices, bank accounts, loans, digital wallets, business products, investments, and retirement schemes, understanding what you’re choosing has never been more important.

Here are the compelling reasons why a financial form guide is not just useful, but essential:

  1. Better Understanding Leads to Better Decisions

Most financial products look similar on the surface. Interest rates, fees, minimum balances, terms, … they all blur together. A form guide reveals the true differences: financial stability, long-term performance, risk management discipline, customer experience, and operational soundness.

This deeper understanding:

  • Reduces poor decision-making
  • Helps avoid risks and weak performers
  • Improves confidence in product selection
  1. It Creates Transparency in Markets That Often Lack It

Banking transparency varies widely, especially in emerging markets.
A structured form guide:

  • Highlights strengths AND weaknesses
  • Shows where performance deviates from the industry
  • Gives consumers a baseline for evaluating claims or advertisements

Transparency reduces uncertainty—and uncertainty is costly.  

  1. It Levels the Playing Field

Large institutions have dedicated research teams. Most consumers and small businesses do not.
A two-page research summary puts professional-grade insights into the hands of everyday decision-makers.

This democratisation of information is one of the most powerful aspects of financial ratings and research.

  1. It Helps Identify Long-Term Trends and Risks

A product may look strong today but show signs of deterioration over time.
A form guide that incorporates five-year trends, peer comparisons, and risk metrics helps users evaluate not only where a bank is, but where it is going.

This forward-looking insight is invaluable for:

  • Long-term savers
  • Business owners
  • Institutional analysts
  • Investors
  • Policy observers
  1. It Encourages Better Behaviour from Banks

When banks know they are being independently assessed, benchmarked, and scored, they have a stronger incentive to:

  • Strengthen governance
  • Improve customer experience
  • Manage risk more prudently
  • Enhance financial resilience

A well-designed rating system becomes a catalyst for industry improvement.

Learning from Ratings Scorecards That Drive Clarity

The Ratings Scorecard is a great example of how a structured, visually-driven analysis tool can help users cut through complexity.
Ratings Scorecards uses:

  • Factor-weighted scoring
  • Objective performance measures
  • Peer group comparisons
  • Transparent methodology

SuperBankRatings adopts these ethos, but adapted to the banking landscape, focusing on stability, strength, and performance rather than investment returns.

The underlying principle is the same: simple, transparent, evidence-based evaluation.

Conclusion: A Modern Form Guide for Modern Financial Decisions

A racing form guide helps punters make informed decisions in an unpredictable environment. Likewise, the SuperBankRatings Form Guide helps consumers navigate the equally unpredictable world of banking.

It condenses complex data into a simple, powerful, two-page summary that:

  • Highlights strengths
  • Identifies weaknesses
  • Benchmarks performance
  • Increases transparency
  • Supports confident decision-making

I n an age where financial choices are increasing and risks are rising, a clear, structured, independent guide is not simply helpful.
It is essential. The form guide at the races may help you back a winner. The Financial Form Guide may help you choose one !

For more information, please contact QnA@SuperBankRatings.com